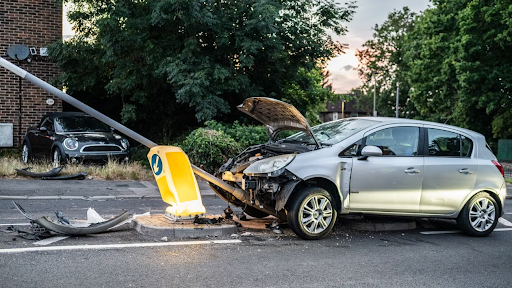
No one gets behind the wheel expecting a collision, yet crashes happen on American roads every single day. In the seconds after impact, shock and adrenaline take over, and the choices a driver makes in those first minutes can shape an injury claim for months or even years. At their core, car accident injury claims are formal requests to an insurance company or a court for money to cover medical bills, lost wages, and other losses tied to the wreck.
Here is the catch. The rules are not the same everywhere. Coverage limits, fault standards, and filing deadlines shift from state to state, and one wrong move can quietly shrink what you recover. Admitting blame at the scene or accepting a settlement before understanding the full extent of your losses are two common mistakes. Whether you settle a minor fender-bender on your own or bring in an experienced Jacksonville personal injury lawyer for a serious crash, the basics below apply to every driver on the road.
Know What You’re Up Against With Car Accident Injury Claims
Car crashes are more common, and potentially more expensive, than many drivers assume. A glance at the national picture helps explain why injury claims require careful documentation:
- In 2024, 39,254 people were killed in motor vehicle crashes in the United States, according to the National Highway Traffic Safety Administration.
- The value of an auto injury claim can vary widely based on the injuries, available coverage, evidence, fault rules, and long-term financial losses.
- Many bodily injury claims resolve through negotiated settlements, but no national percentage or average settlement figure can predict the result of an individual case.
Take the Right Steps at the Scene
What you do in the first hour can affect a later claim. Work through this checklist before you leave the crash site, provided it is safe and medically reasonable to do so:
- Call the police. An officer’s report creates an official record of reported information, observations, and the parties involved. Reporting requirements vary by state and by the severity of the crash.
- Check for injuries and move to safety. Get yourself and your vehicle out of active traffic if you can do so safely, then call for medical help when needed.
- Photograph everything. Capture vehicle damage from several angles, skid marks, traffic signals, road conditions, license plates, and any visible injuries without placing yourself in danger.
- Exchange details. Collect names, phone numbers, driver’s license information, plate numbers, and insurance details from every driver involved, plus contact information for witnesses.
- Guard your words. Be polite, but avoid guessing about fault or making admissions before all the facts are known. Let the available evidence determine responsibility.
Gauge Magazine’s guide explaining what to do immediately after a car accident provides additional guidance on safety, medical attention, insurance notification, and record preservation.
Let the Evidence Tell the Story
Strong claims rest on documentation, not memory. Adjusters look for gaps and inconsistencies, so the more you can support your account with reliable records, the better.
Your own photographs matter, and so do outside sources. Police reports, dashcam footage, and available traffic-camera video can help show how a particular collision occurred. National crash data provides broader safety context, although it does not establish fault in an individual collision. Preserve available evidence early because conditions at a crash scene can change quickly.
Don’t Wait on Medical Care
Injuries from a wreck do not always announce themselves immediately. Stress and adrenaline can temporarily mask symptoms associated with whiplash, concussions, soft-tissue injuries, and other conditions.
- See a doctor promptly. A timely examination can identify injuries that require treatment and create a contemporaneous medical record. Timing can support the medical history, although it does not by itself prove that the crash caused an injury.
- Follow the plan. Follow the treatment recommendations given by your medical providers and explain unavoidable gaps or missed appointments. Insurers may question unexplained interruptions in care.
- Keep records. Save bills, discharge notes, prescriptions, test results, and a log of every workday you miss.
These medical records work alongside photographs, witness information, and other factors that can help build a strong car accident claim.
Understand Your State’s Rules
Three legal concepts can affect what drivers recover after the common crashes most drivers face:
- Fault versus no-fault: In a fault-based system, the responsible driver’s liability coverage may pay qualifying losses. In no-fault states, certain benefits may initially come from an injured person’s own policy regardless of who caused the crash. The available benefits, limits, deductibles, and right to pursue another driver vary by state.
- Comparative or contributory negligence: States use different rules when an injured person shares responsibility. Some reduce compensation according to the person’s percentage of fault, some prevent recovery at a specified threshold, and a small number apply stricter contributory-negligence rules.
- Statute of limitations: Every state establishes filing deadlines, but the applicable period varies. Claims involving a government entity, a minor, a death, or another special circumstance may follow different notice requirements or deadlines.
File and Negotiate Carefully
Once treatment is underway, the claim itself begins. A few habits can help protect your interests:
- Report promptly and factually. Notify your insurer within the time required by your policy and stick to information you actually know.
- Handle adjusters with care. Understand who is requesting a recorded statement and what your policy requires. Your own insurer may require cooperation, while another driver’s insurer does not represent you. Keep answers factual and seek advice if you are unsure about your obligations. Review any settlement offer carefully because it may arrive before the full extent of treatment, lost income, or future expenses is known.
- Count all your damages. A complete claim may include economic losses such as medical costs, future treatment, and lost income, along with legally recoverable non-economic losses such as pain and suffering.
Conclusion
A car accident injury claim rewards drivers who act promptly, document carefully, and understand the rules where they live. You cannot prevent every crash, but you can control how prepared you are when one happens, and that readiness can protect both your financial interests and your peace of mind.
This article provides general information and is not legal advice. Insurance requirements, filing deadlines, and compensation rules depend on the applicable state law, policy language, and facts of the collision.
The post What Every Driver Should Know About Car Accident Injury Claims appeared first on Gauge Magazine.