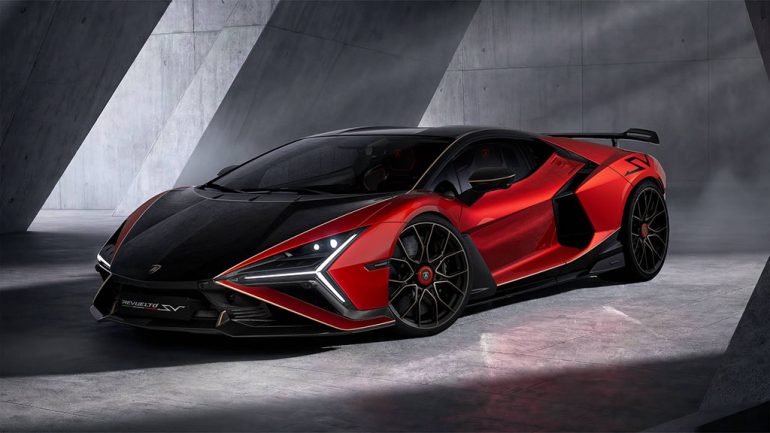
Owning your dream car is an exciting financial goal, whether you have your eyes on a luxury sedan, a powerful sports car or a comfortable SUV. However, turning that dream into reality requires more than enthusiasm and a steady paycheck. It takes financial discipline, careful planning and a clear understanding of how your everyday money decisions affect your ability to make a major purchase.
Many people assume that buying their ideal vehicle requires a significant increase in income. While earning more certainly helps, developing smarter financial habits can be equally important. Small changes in spending, saving and debt management can gradually free up money that brings your dream car closer.
The key is to approach vehicle ownership as a planned financial achievement rather than an impulsive purchase. By establishing realistic goals and making consistent decisions, you can work toward owning the car you want without compromising your overall financial stability.
Before creating a savings plan, determine exactly what you want to purchase. Research different models, compare their features and establish a realistic price range based on your financial circumstances.
However, the manufacturer’s suggested retail price is only one part of the equation. Vehicle ownership involves several additional expenses, including insurance premiums, registration fees, maintenance, fuel and potential repairs.
A luxury vehicle may seem affordable based on its monthly financing payment, but higher insurance rates and maintenance expenses could make ownership considerably more expensive than expected.
Start by estimating the total cost of purchasing and maintaining your preferred vehicle. Consider how much money you can reasonably allocate toward transportation without interfering with essential living expenses or long-term savings.
Having a clear target also makes it easier to measure progress. Instead of vaguely hoping to purchase a vehicle someday, you can establish a specific savings amount and a realistic timeline for achieving it.
One of the most effective ways to achieve a major financial goal is to separate the money intended for that purpose from your everyday spending funds.
Opening a dedicated savings account for your vehicle purchase allows you to track your progress while reducing the temptation to spend the money on unrelated expenses.
Consider setting up automatic transfers from your checking account into this dedicated fund immediately after receiving your paycheck. This approach helps establish consistency because saving becomes part of your regular financial routine.
For example, putting aside $350 every month would allow you to accumulate $4,200 in one year, excluding any interest earned. Increasing your monthly contribution as your income grows could accelerate your progress further.
A high-yield savings account may also help your money grow while keeping it accessible for a purchase you expect to make within the next few years.
The most important factor is consistency. Regular contributions, even when relatively small, can accumulate into a meaningful down payment over time.
Budgeting is not simply about restricting spending. It is about understanding where your money goes and ensuring that your financial decisions reflect your priorities.
Begin by reviewing your monthly income and categorizing your expenses into essential obligations, discretionary purchases and savings contributions.
Housing, utilities, groceries and existing debt payments usually take priority. However, discretionary expenses often provide opportunities to redirect money toward your vehicle savings goal.
For instance, reducing restaurant spending, limiting unused subscriptions or choosing more affordable entertainment options could create additional room in your budget.
You do not necessarily need to eliminate every enjoyable purchase. Instead, identify spending habits that offer relatively little value compared with your goal of owning your dream car.
Tracking expenses through budgeting applications can make this process easier. Many modern financial tools automatically categorize transactions and provide insights into spending patterns, allowing you to identify potential savings opportunities.
Review your budget regularly as your income, expenses and priorities change.
Credit cards can be useful financial tools when managed responsibly. Beyond providing convenient payment options, some cards offer cashback, travel benefits or reward points on qualifying purchases.
If you already use credit cards for regular expenses, understanding how their reward structures work may help you obtain additional value from spending you would have done anyway.
For example, certain cards provide higher rewards for groceries, fuel or dining purchases. Consumers who compare ways to earn reward points for different cards can identify options that better match their existing spending habits and financial priorities.
Depending on the card’s redemption terms, accumulated rewards might help offset certain expenses, freeing up additional money for your vehicle savings fund.
However, earning rewards should never encourage unnecessary purchases. Carrying a balance and paying high interest charges can quickly eliminate the financial benefit of cashback or reward points.
The most effective approach is to use credit cards for planned expenses, pay the statement balance in full whenever possible and avoid treating available credit as additional income.
Used carefully, rewards programs can complement a broader savings strategy without creating unnecessary debt.
Unless you plan to purchase your dream car entirely with cash, your credit profile will likely influence the financing options available to you.
Lenders commonly evaluate credit history, income, existing debt and other financial factors when determining loan eligibility and interest rates.
A stronger credit profile may help you qualify for more favorable financing terms, potentially reducing the total cost of purchasing your vehicle.
Several habits can support healthier credit over time, including paying bills on schedule, keeping credit card balances manageable and avoiding unnecessary applications for new credit.
It is also worth reviewing your credit reports periodically to identify inaccurate information that could affect lending decisions.
Remember that a lower monthly payment does not automatically mean a better financing deal. Longer loan terms may reduce monthly obligations while increasing the total interest paid.
Focus on the overall cost of borrowing rather than evaluating affordability based on monthly payments alone.
Existing debt can make saving for a vehicle challenging, particularly when a significant portion of monthly income goes toward interest payments.
Credit card balances and high-interest personal loans can consume money that might otherwise support your automotive goals.
Consider developing a structured repayment strategy that prioritizes expensive debt while maintaining essential savings.
One common approach is the debt avalanche method, which focuses additional payments on debts with the highest interest rates first. This can reduce the amount paid in interest over time.
Alternatively, some individuals prefer paying off smaller balances first to build motivation and establish momentum.
Whichever strategy you choose, the objective is to reduce financial obligations and create greater flexibility within your monthly budget.
Eliminating expensive debt before financing a vehicle may also improve your debt-to-income ratio, an important consideration for many lenders.
Reducing unnecessary expenses can accelerate your savings progress, but increasing your income can make an equally meaningful difference.
Consider whether your existing skills could support freelance work, consulting services or a small side business.
Other possibilities include negotiating a salary increase, pursuing professional certifications or accepting occasional additional work when your schedule allows.
Selling unused electronics, furniture or other valuable items can also provide an immediate contribution to your vehicle savings fund.
Rather than allowing additional earnings to blend into your everyday spending, consider directing a substantial portion toward your automotive goal.
This approach helps ensure that extra income produces visible progress instead of gradually disappearing through lifestyle inflation.
However, avoid overcommitting yourself to additional work that could negatively affect your health, primary employment or personal responsibilities.
Buying your dream car is achievable when you combine realistic expectations with consistent financial habits. Creating a dedicated savings fund, controlling unnecessary expenses, managing credit responsibly and researching financing options can all help shorten the distance between your current situation and your automotive ambitions.
Progress does not always require dramatic financial changes. Often, it comes from a series of practical decisions repeated over months or years.
By maintaining discipline and keeping your broader financial goals in mind, you can work toward owning the vehicle you have always wanted while preserving the financial stability that makes the achievement truly worthwhile.