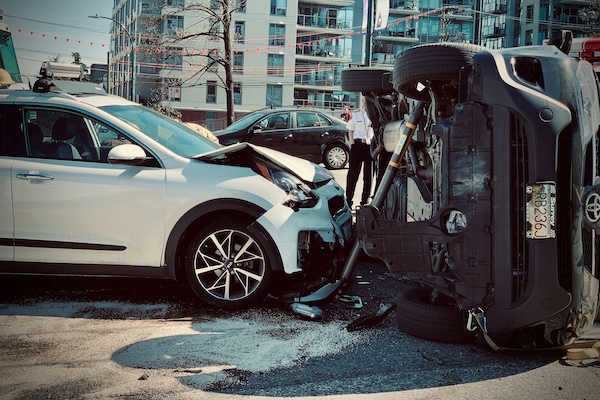
Fort Lauderdale’s busy roads, growing neighborhoods, and steady flow of daily traffic make car accidents an unfortunate reality for many local residents. Beyond the immediate shock of a collision, those involved may face medical expenses, time away from work, and uncertainty about how to move forward. For someone already dealing with the physical and financial effects of an accident, receiving a settlement offer can seem like a welcome opportunity to put the experience behind them.
However, an early offer does not always reflect the full extent of the losses or the long-term effects of an injury. Accepting the wrong terms can leave an injured person with expenses they never expected to handle alone. Before deciding, it helps to understand what a fair settlement should cover. You can speak with a car accident attorney to help clarify the offer, identify potential concerns, and protect your legal interests.
An early offer may leave out care that hasn’t happened yet. A neck injury, for instance, could require follow-up appointments, imaging, or therapy after an initial evaluation. If the settlement releases future claims, the injured person could be responsible for later expenses tied to the same crash.
Before responding, compare the amount with bills received, recommended care, prescriptions, travel to appointments, and time away from work. Ask the insurer to explain how it calculated each category. Without a clear breakdown, it is difficult to assess the number.
The payment amount is only one part of the decision. A release may waive claims against a driver, an insurer, or another party. Its wording could cover losses beyond immediate medical bills. Read the full document, including definitions and clauses about liens or repayment.
If the release is unclear, an injured person can speak with a car accident attorney to review which rights the document would end. A review is useful when treatment continues, fault is disputed, or the paperwork names parties beyond the driver. Before signing, identify questions that need answers instead of treating the payment as the only term that matters.
A low figure may omit expenses or losses the claimant can document. Check whether the calculation includes medical charges, lost wages, out-of-pocket costs, and the injury’s effect on ordinary tasks. Keep receipts, pay records, appointment notes, and written recommendations together to support each claimed loss.
A settlement statement does not necessarily list every loss. Compare its categories with the records, then ask for an explanation if an item is missing or reduced. If the insurer disputes an expense, point to the supporting document and request a written response.
A short deadline, repeated calls, or warnings that an offer will disappear can rush someone into deciding before reviewing the file. Ask for the offer and release in writing. Confirm the response deadline and whether the insurer will consider a written counteroffer. Keep a record of calls and messages.
A firm deadline does not show whether the amount is fair. Take time to compare the paperwork with treatment records and expenses. If the deadline is unclear, request clarification rather than relying on a verbal summary.
An offer may be reduced because the insurer blames the claimant for part of the crash. Ask which facts support that position, such as a witness account, photographs, vehicle damage, or a crash report. Compare those materials with the claimant’s records and note gaps or inconsistencies.
Florida uses comparative fault, but its effect depends on the case facts and applicable rules. An adjuster’s stated percentage does not, by itself, prove what happened. Before evaluating a reduced offer, ask which evidence supports the proposed share of fault.
Check who will issue the payment, which documents must be signed first, and whether the offer accounts for health plans or other parties seeking repayment. A settlement can be delayed or reduced if those interests remain unresolved. Ask the insurer to explain deductions and identify unpaid amounts.
Confirm whether the document also requires confidentiality or restricts statements about the crash. These terms can matter after payment. If a verbal assurance conflicts with the written agreement, ask for corrected terms before signing.
Judge a settlement against documented losses, the expected course of care, and the release’s exact wording, not just the check amount. Put the offer beside medical records, bills, and wage documents, then list unexplained reductions or unanswered terms. If signing would end claims while important details remain uncertain, pause and have the document reviewed before accepting.